Closing Costs Unpacked: State-by-State Breakdowns for Today’s Buyers

If you’re planning to buy a home this year, there’s one expense you can’t afford to overlook: closing costs.

Almost every buyer knows they exist, but not that many know exactly what they cover, or how different they can be based on where you’re buying. So, let’s break them down.

What Are Closing Costs?

Your closing costs are the additional fees and payments you make when finalizing your home purchase. Every buyer has them. According to Freddie Mac, they typically include things like homeowner insurance and title insurance, as well as various fees for your:

  • Loan application
  • Credit report
  • Loan origination
  • Home appraisal
  • Home inspection
  • Property survey
  • Attorney

National vs. Local: Why the Numbers Look So Different

When you search for information about closing costs online, you’ll often see a national range, usually 2% to 5% of the home’s purchase price. While that’s a useful starting point if you’re working on your homebuying budget, it doesn’t tell the whole story. In reality, your closing costs will also vary based on:

  • Taxes and fees where you live (like transfer taxes and recording fees)
  • Service costs for things like title and attorney work in your local area

While the home price is obviously going to matter, state laws, tax rates, and even the going costs for title and attorney services can change what you expect to pay. That’s why it’s important to talk to the pros ahead of time so you know what to budget for. It can put you in control before you even start shopping.

To give you a rough ballpark, here’s a state-by-state look at typical closing costs right now based on those factors for the median-priced home in each state (see map below):
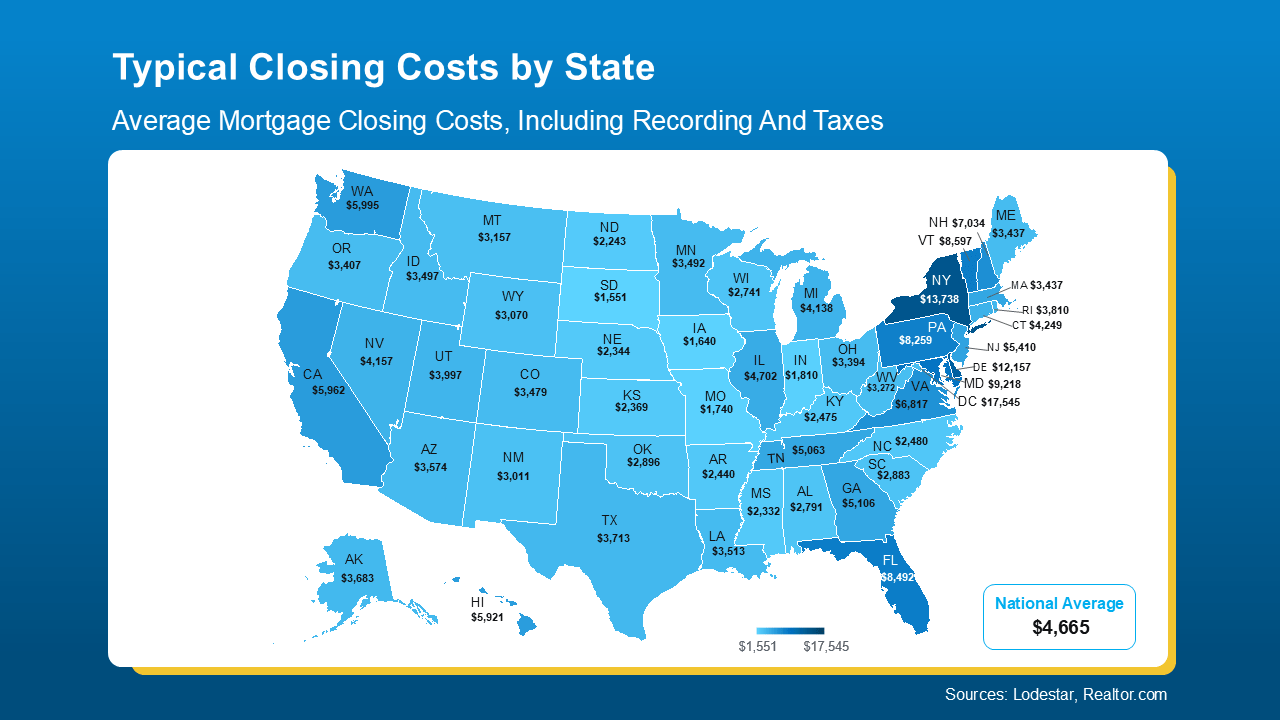
Closing Costs Unpacked: State-by-State Breakdowns for Today’s Buyers | North Scottsdale Real Estate & Luxury Homes | Team PicarelloAs the map shows, in some states, typical closing costs are just roughly $1-3K. In a few places, they can be closer to $10-15K. That’s a big swing, especially if you’re buying your first home. And that’s why knowing what to expect matters.

If you want a real number to help with your budget, your best bet is to talk to a local agent and a lender. They can run the math for your price range, loan type, and exact location.

And just in case you’re looking at your state’s number and wondering if there’s any way to trim that bill, NerdWallet shares a few strategies that can help:

  • Negotiate with the seller. Ask for concessions like a credit toward your closing costs.
  • Shop around for homeowner’s insurance. Compare coverage and rates before you commit.
  • Check for assistance programs. Some states, professions, and neighborhoods offer help. Your agent and lender can point you to what’s available locally.

Bottom Line

Closing costs are a key part of buying a home, but they can vary more than most people realize. Knowing your numbers (and how to potentially bring them down) can go a long way and help you feel confident about your purchase.

Let’s look at typical closing costs in our area and get you a personalized estimate, so you can craft your ideal budget.
Why Now May Be a Key 2025 Moment To Sell Your House

Mortgage rates are finally heading in the right direction – and buyers are starting to jump back in.

According to the data, buyer demand picked up considerably once mortgage rates hit a new low for 2025. The Mortgage Bankers Association (MBA) reports that applications for home loans were up 23% compared to the first week of September last year.

If you’ve been waiting to sell, or your listing recently expired because the market was slower than you hoped it would be, now’s the time to reconsider your move. Buyer demand is the highest it’s been since July – and you don’t want to miss this window.

When Rates Drop, Buyers React

Here’s what’s happening. The 30-year mortgage rate dropped to 6.13% earlier this week. And that’s the lowest it had been since October 2024. That decline followed weak job growth and other economic indicators that are fueling speculation the Federal Reserve may cut the Federal Funds Rate multiple times this year. Mortgage rates started dropping because financial markets are anticipating those Fed decisions. And that opens the door for more buyers to act.

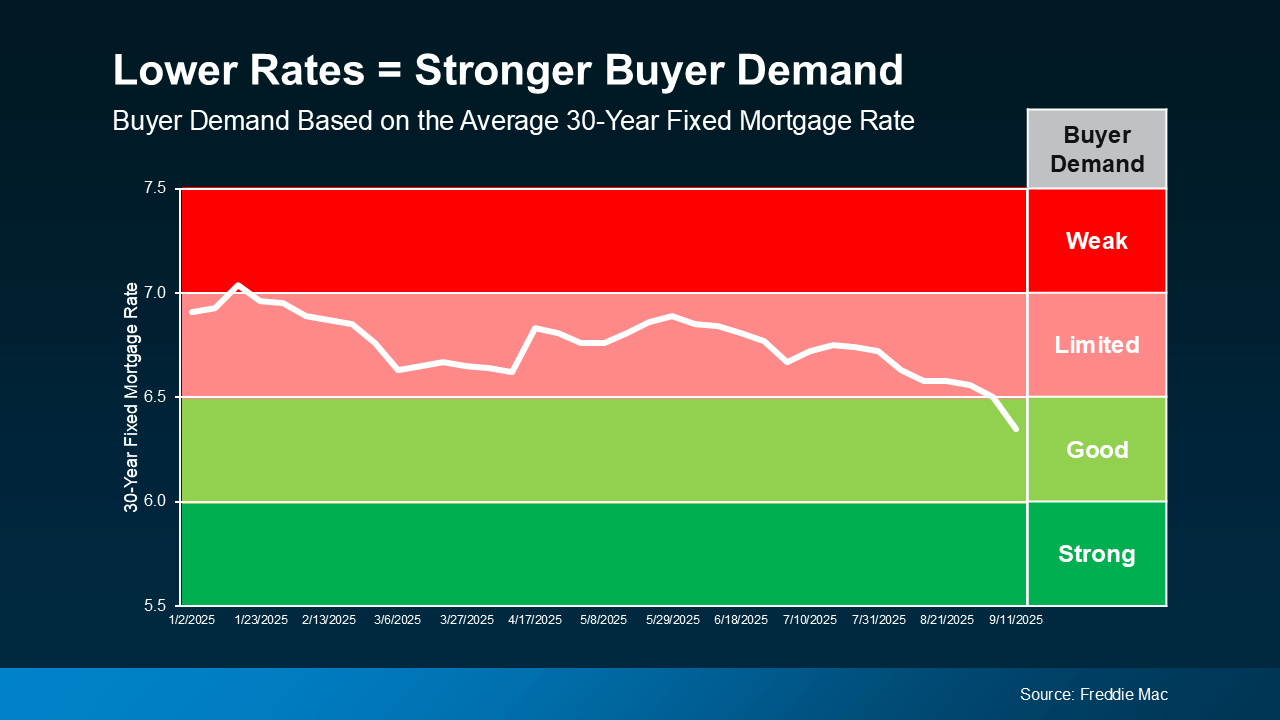
Since today’s buyers are looking at every angle to make home purchases more affordable, they’re much more sensitive to even the slightest movement in mortgage rates. Basically, it boils down to this. As affordability improves, so does buyer demand (see graph below):

a graph of a graph showing a rise in mortgage rateAnd that’s a change you’re going to feel – in a good way. Since about this time last year, we’ve been in a plateau of “limited” buyer demand. But now that rates are coming down, buyer demand is getting better.

What This Means for You

If you’re looking to move, it’s time to get serious about what’s happening in the market, and how you can use these key moments to your advantage. Maybe you have an expired listing that sat without offers earlier this year, or you held off on selling altogether, thinking buyers weren’t out there. This is your signal – they’re coming back. Now, it’s not in the big surge the market saw a few years ago, but this could be your window.

Here’s the opportunity. You can list, while buyer activity is rising and before more sellers in your neighborhood do too. Other homeowners may not see this shift for a while, so you can get a leg up on your competition if you act now.

On the flip side, if you wait, sure there may be more buyers if rates continue to inch down. But there are also going to be more sellers too. So, why take that risk?

A trusted local agent can help you assess your home’s value, fine-tune your pricing strategy, and make sure it stands out to the serious buyers who are taking action today.

Bottom Line

Buyers are watching rates, weighing their options, and starting to get off the sidelines. If you’re thinking about selling, this may be your chance to get ahead.

Want to make sure your house shows up for the right buyers, at the right time?

Let’s connect and walk through the steps together so you can make the most of this moment.

Mortgage Rates Just Saw Their Biggest Drop in a Year

You’ve been waiting for what feels like forever for mortgage rates to finally budge. And last week, they did – in a big way.

On Friday, September 5th, the average 30-year fixed mortgage rate fell to the lowest level since October 2024. It was the biggest one-day decline in over a year.

What Sparked the Drop?

According to Mortgage News Daily, this was a reaction to the August jobs report, which came out weaker-than-expected for a second month in a row. That sent signals across the financial markets, and then mortgage rates came down as a result.

Basically, we’re seeing signs the economy may be slowing down, and as certainty grows in the direction the economy is going, the markets are reacting to what is likely ahead. That historically brings mortgage rates down.

Why Buyers Should Pay Attention Now

But this isn’t just about one day of headlines or one report. It’s about what the drop means for you.

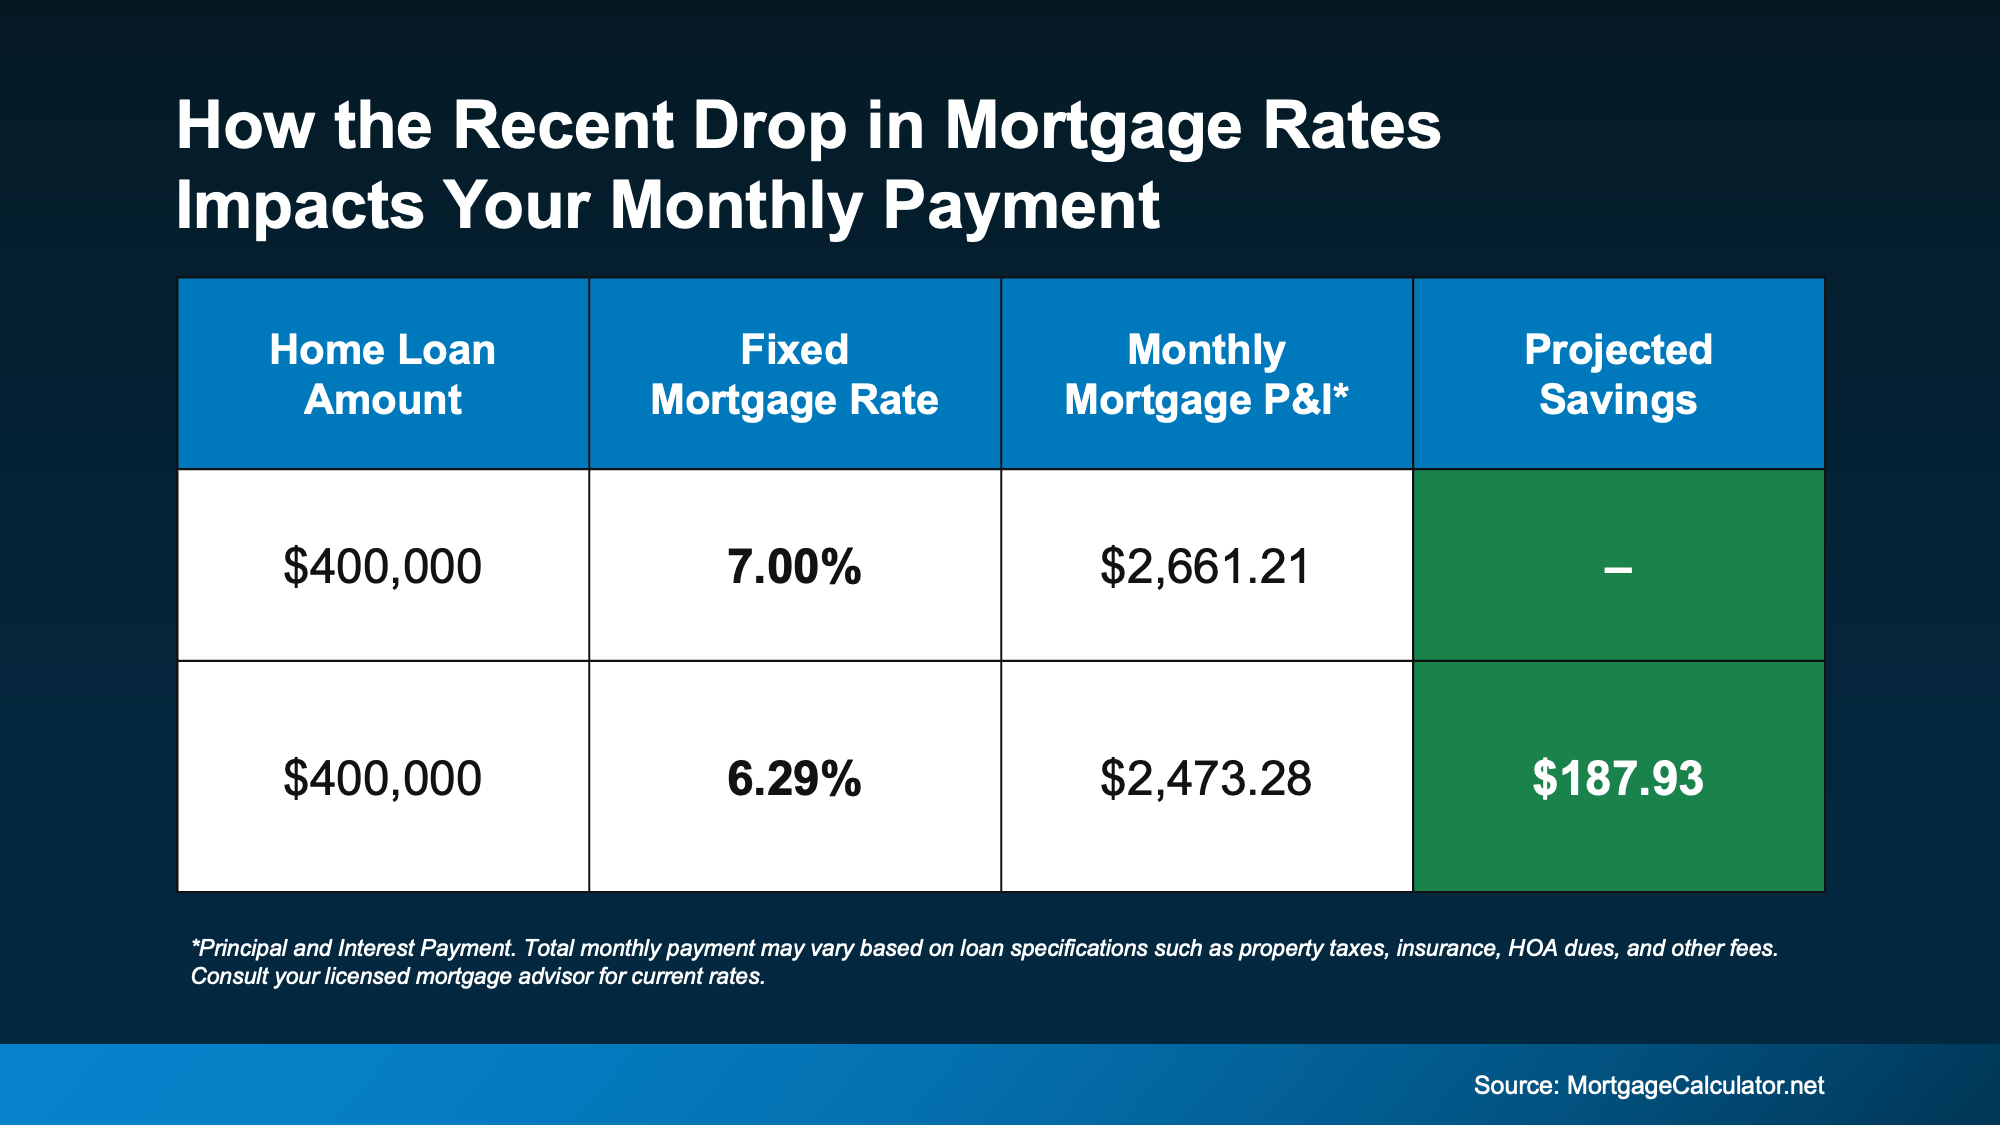
This recent change saves you money when you buy a home. The chart below shows you an example of what a monthly mortgage payment (principal and interest) would be at 7% (where mortgage rates were in May) versus where rates roughly are now:

Mortgage Rates Just Saw Their Biggest Drop in a Year | North Scottsdale Real Estate & Luxury Homes | Team PicarelloCompared to just 4 months ago, your future monthly payment would be almost $200 less per month. That’s close to $2,400 a year in savings.
How Long Will It Last?

That really depends on where the economy and inflation go from here. Rates could drop lower, or they could inch up slightly.

So, make sure you’re connected with a good agent and trusted lender. They’ll keep a close eye on inflation indicators, job market updates, and reactions to upcoming Fed policy to gauge where mortgage rates may go from here.

But for now, focus on this. While no one can say for sure where rates are headed, the fact that rates broke out of their months-long rut is a good thing. If you’ve been feeling stuck, this could make the start of a new chapter. As Diana Olick, Senior Real Estate and Climate Correspondent at CNBC, says:

“Rates are finally breaking out of the high 6% range, where they’ve been stuck for months.” 

And that’s gives you more reason to hope than you’ve had in quite some time.

Bottom Line

This is the shift you’ve been waiting for.

Mortgage rates just saw their biggest decline in over a year. And if rates stay near this level, it could make a home you couldn’t afford just a few months ago feel possible again.

What would today’s rates save you on your future monthly payment? Let’s connect so you can find out.

Builder Incentives Reach 5-Year High

Even with more homes on the market right now, some buyers are still having a tough time finding the right one at the right price. Maybe the layout feels off. Maybe it still needs some updating. Or maybe it’s just more of the same.

That’s why more buyers are turning to new construction – and finding some of the best deals available today.

Why? Today, many builders have more homes that are finished and sitting on the market than normal. And that means they’re motivated to sell. They’re running a business, and they don’t want to sit on their inventory. They want to sell it before they build more homes. And that can definitely work in your favor.

As Lance Lambert, Co-Founder of ResiClub, puts it:

“In housing markets where unsold completed inventory has built up, many homebuilders have pulled back on their spec builds—and many are doing bigger incentives or outright price cuts to move unsold inventory.”

Incentives Are the Highest They’ve Been in 5 Years

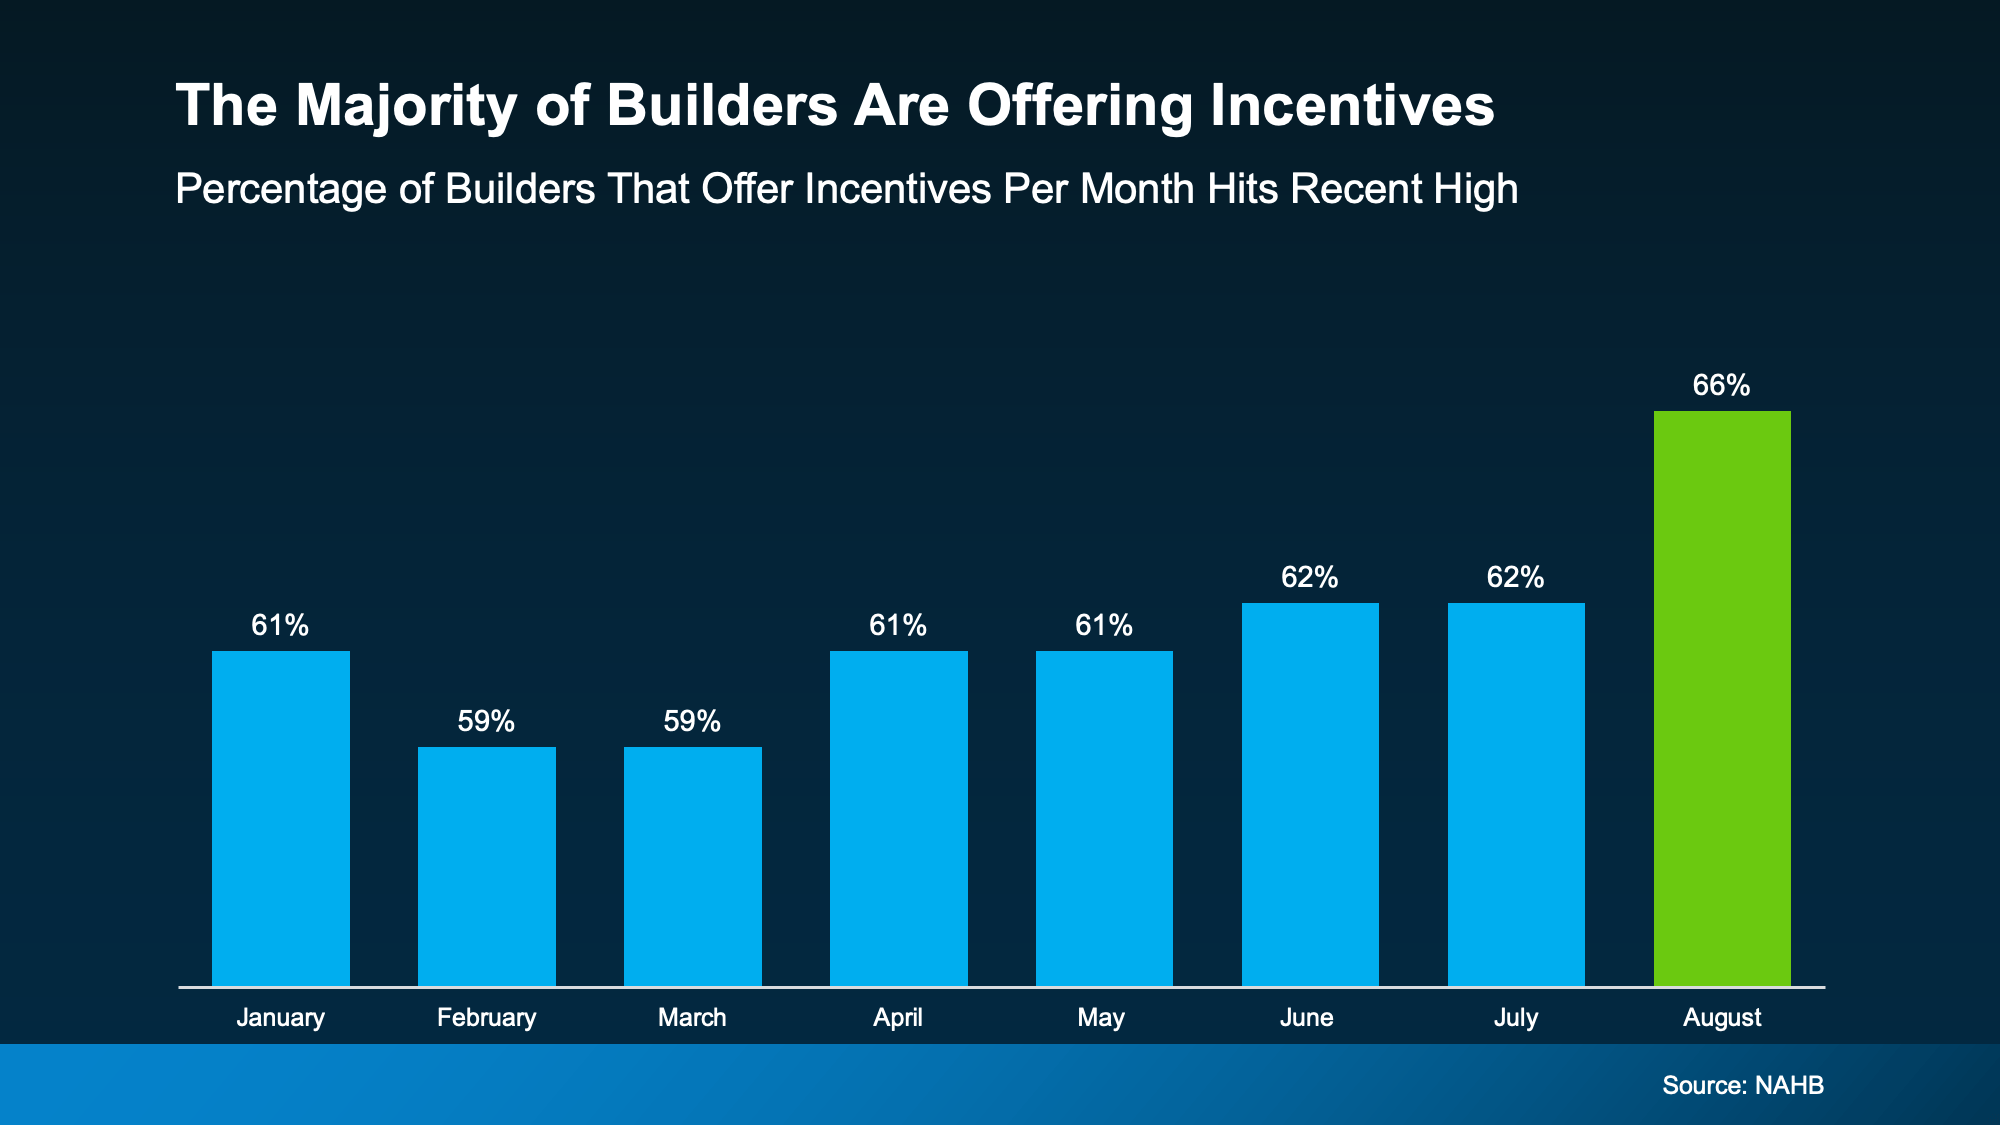
Data from the National Association of Home Builders (NAHB) shows 66% of builders offered sales incentives in August. That’s the peak so far this year, and the highest percentage we’ve seen in 5 years.

a graph of blue rectangular bars with numbersThat means 2 out of every 3 builders are offering something extra to get deals done. And when builders throw in incentives, it’s the buyers like you who win.

Price Cuts Are Back on the Table

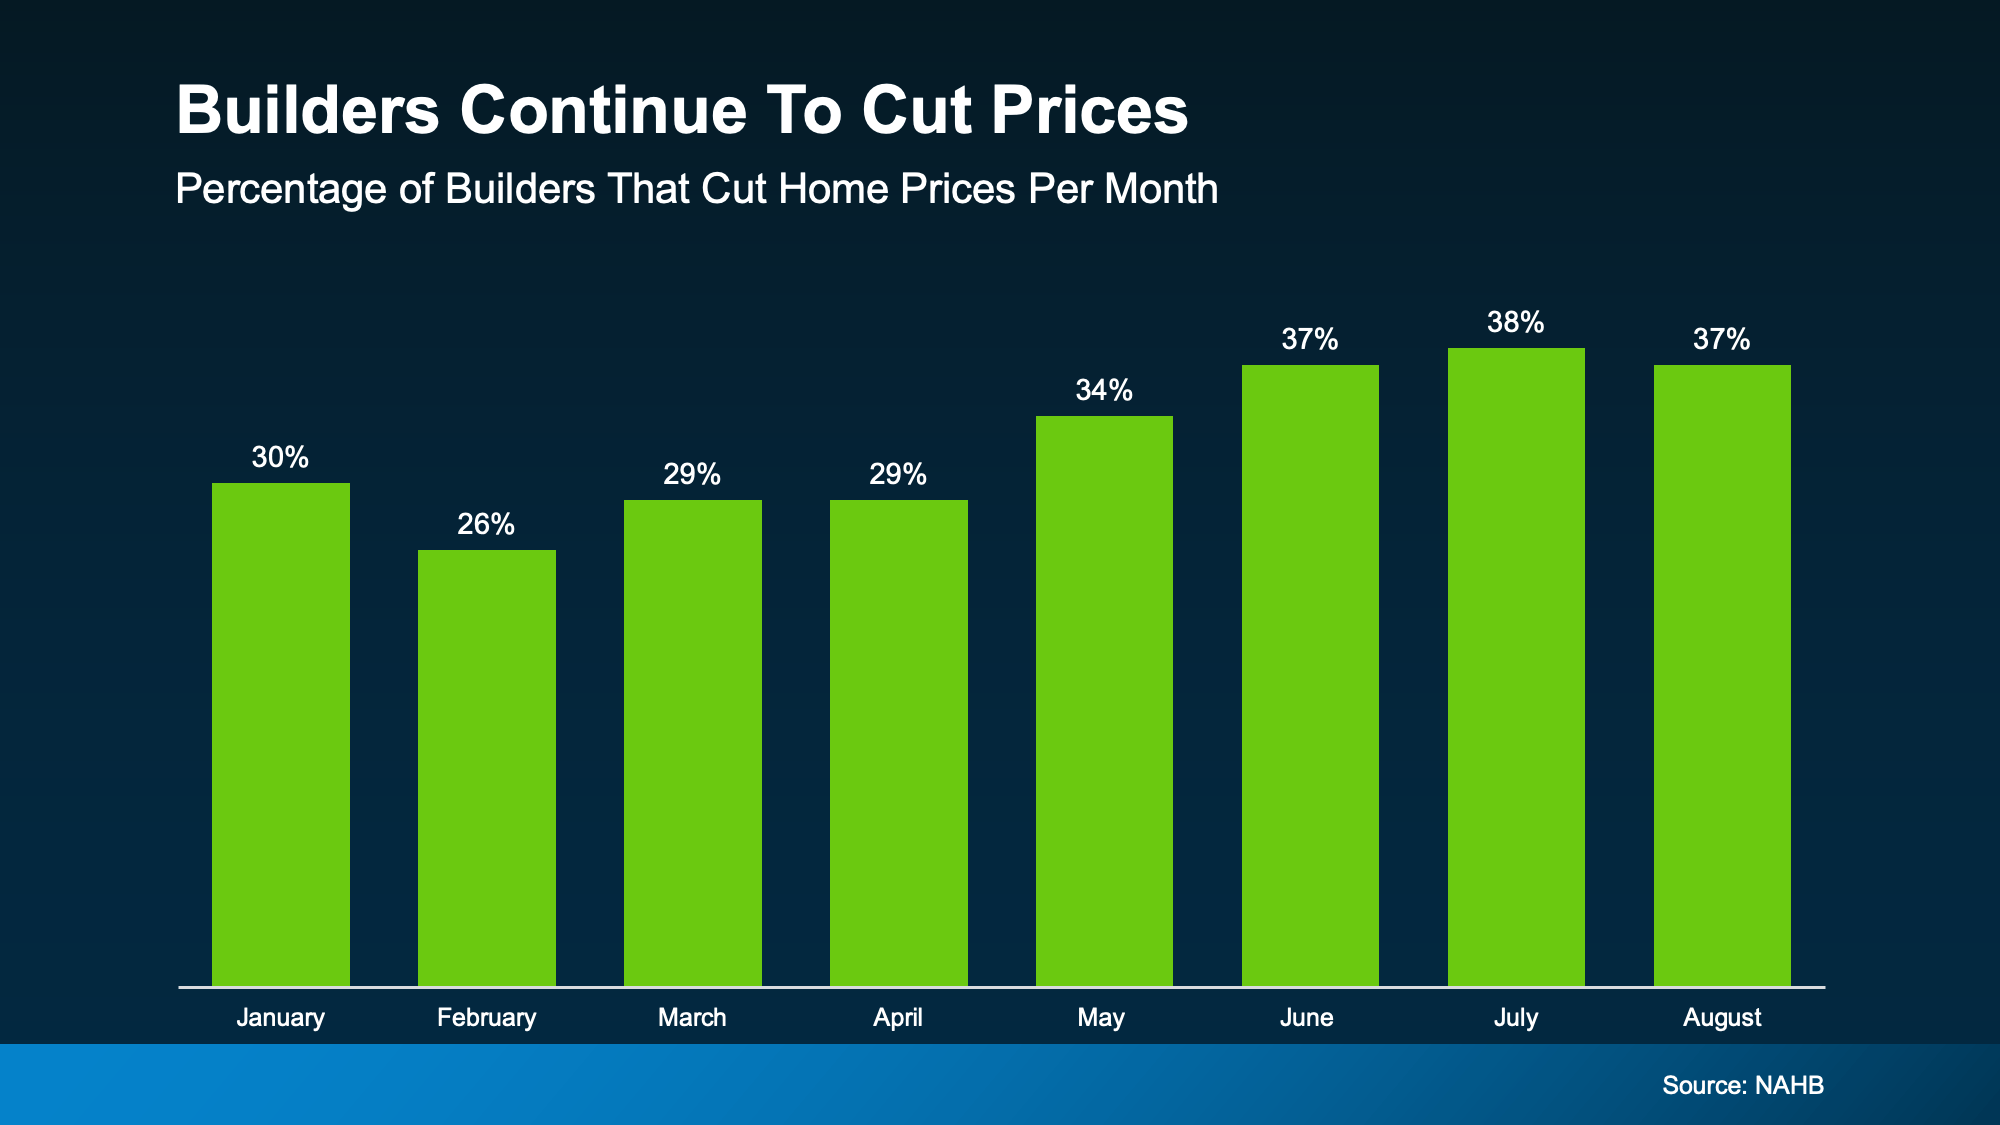
One of the most common incentives they’re offering right now is adjusting the price. According to NAHB, almost 40% of builders are doing price cuts (see graph below):

Builder Incentives Reach 5-Year High | North Scottsdale Real Estate & Luxury Homes | Team PicarelloOn average they’re taking off about 5% off the purchase price of the house. For a buyer, 5% could be the difference between reluctantly settling and finally getting a home that works for you.
Take a $500,000 house as an example. If builders reduce the price by 5%, you’re saving $25,000.

And even if the builder you’re interested in won’t budge on price, they’ve got plenty of other levers to pull. As Realtor.com explains:

“. . . there are deals to be found in the market for new homes, with builders increasingly willing to negotiate on price or offer incentives such as rate buydowns and closing cost assistance.”

Why This Matters for You

As a buyer, you probably have a clear vision for your ideal home. Because you’re not just buying any house. You’re buying your house. The one with the space, features, and lifestyle you’ve been hoping for. New builds can check those boxes since they usually have:

  • Bigger kitchens and open layouts
  • Energy efficiency (hello lower utility bills)
  • Smart-home upgrades
  • Fewer repair headaches on day one

And today’s incentives make buying a new home more attainable than it’s been in years.

One Word of Advice: Don’t Go At It Alone

If you want to take advantage of this opportunity, just be sure to use your own agent. Builder reps aren’t there to save you money. They protect the builder’s bottom line. That’s why you need to bring your agent with you. Your agent will:

  • Cut through the sales pitch and run the cold hard numbers
  • Spot which incentives are actually worth it (and which ones are fluff)
  • Handle negotiations so you walk away with the best deal possible
  • Keep your best interest as their top priority

Bottom Line

If you’re not finding a home you love, the new home market is buzzing with opportunity. With record-high incentives, price cuts in play, and builders itching to move inventory, this is the best time in years to buy new construction.

Curious how far today’s incentives could stretch your budget? Let’s connect so you can see what builders are offering in our area.

History Shows the Housing Market Always Recovers

Now that the market is slowing down, homeowners who haven’t sold at the price they were hoping for are increasingly pulling their homes off the market. According to the latest data from Realtor.com, the number of homeowners taking their homes off the market is up 38% since the start of this year and 48% since the same time last June. For every 100 new listings in June, about 21 homes were taken off the market.

And if you’ve made that same choice, you’re probably frustrated things didn’t go the way you wanted. It’s hard when you feel like the market isn’t working with you. But while slowdowns can be painful in the moment, history tells us they don’t last forever.

History Repeats Itself: Proof from the Past

This isn’t the first time the housing market has experienced a slowdown. Here are some other notable times when home sales dropped significantly:

  • 1980s: When mortgage rates climbed past 18%, buyers stopped cold. Sales crawled for years. But as soon as rates came down, sales surged back, and the market found its footing again.
  • 2008: The Great Financial Crisis was one of the toughest housing downturns in history. Sales and prices both dropped hard. Still, sales rebounded once the economy recovered.
  • 2020: During COVID, sales disappeared overnight, and many people had to put their plans on hold. Yet the recovery was faster than anyone expected, with a surge of buyers re-entering the market as soon as restrictions eased.

The lesson is clear: no matter the cause, the market always rebounds.

Today’s Situation: Where We Stand Now

Over the past few years, home sales have been sluggish. And one big reason why is affordability. Mortgage rates rose at a record-breaking pace in 2022, and home prices were climbing at the same time. That combination put buying out of reach for many people. And when demand slows, home sales do too.

The Outlook: Why Things Will Improve

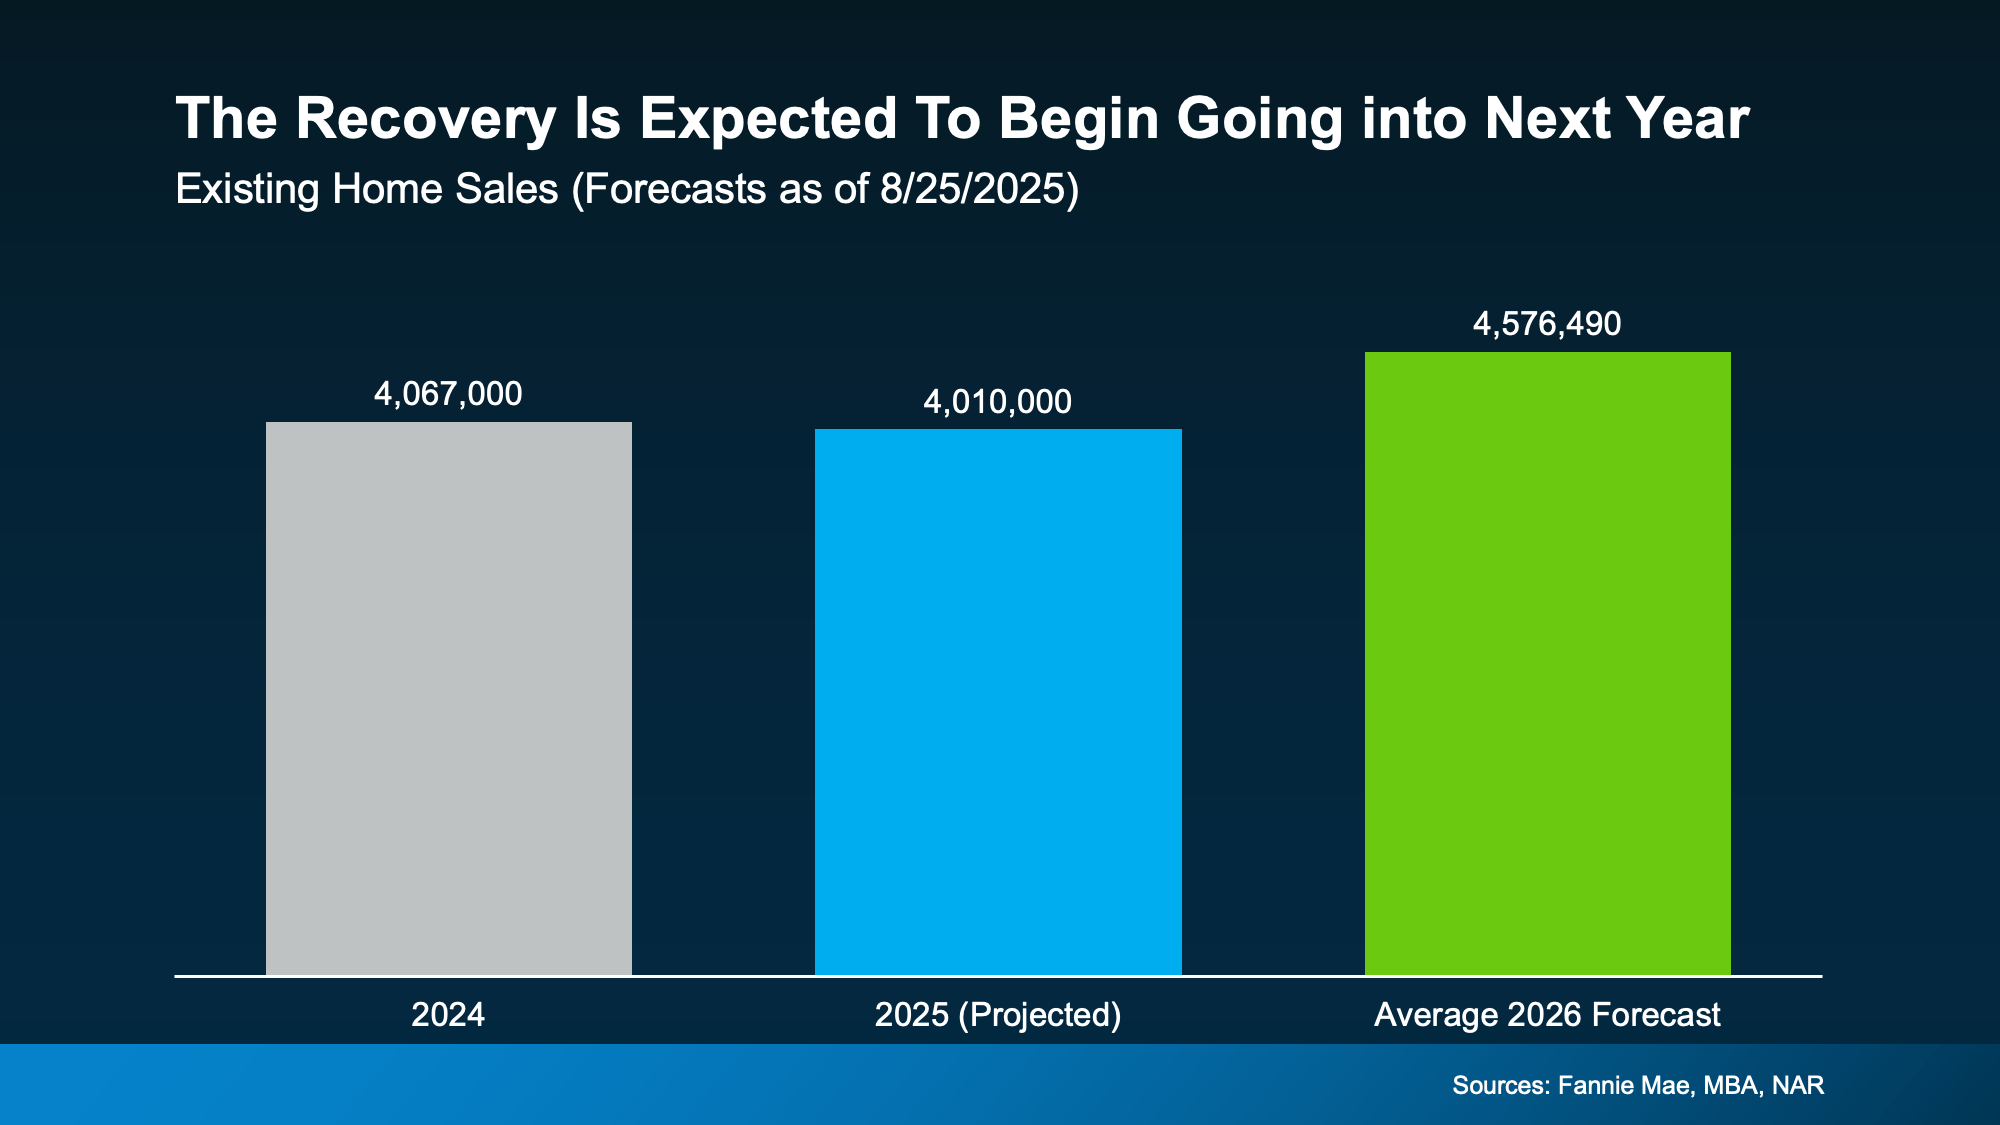
But here’s the encouraging part. Forecasts show sales are expected to pick up again moving into 2026.

Last year, just about 4 million homes sold (shown in gray in the graph below). And this year is looking very similar (shown in blue). But the average of the latest forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), and the National Association of Realtors (NAR) show the experts believe there will be around 4.6 million home sales in 2026 (shown in green).

And a big reason behind that projection is the expectation that mortgage rates will come down a bit, making it easier for more buyers to jump back in.

a graph of salesThat means what’s happening now is part of a cycle we’ve seen before. Every slowdown in the past has eventually given way to more activity, and this one will too.

Just like the 1980s, 2008, and 2020, today’s dip in home sales is temporary.

What That Means for You

If you’ve paused your moving plans, you did what you thought was right. Your frustration is valid. But it’s also important to remember the bigger picture. Housing slowdowns don’t last forever.

That’s where your local real estate agent comes in. Their job is to keep a close eye on the market for you. When the first signs of a rebound appear, they’ll help you spot the shift early so you can relist with confidence.

Bottom Line

If today’s housing market feels stuck, remember it’s never stayed down for good. Slowdowns end, activity returns, and people get moving again. So, let’s connect, because when the next wave of buyers shows up, you won’t want to miss it.

As activity picks up again, will you be ready to put your house back on the market, or do you need to move sooner?