October 2022 Market Update

Note: October 2022 data below are the most recent released by the National Association of Realtors.

Total existing-home sales) completed transactions that include single-family homes, townhomes, condominiums and co-ops) decreased 5.9% from September to a seasonally adjusted annual rate of 4.43 million in October. Year-over-year, sales dropped by 28.4% (down from 6.19 million in October 2021).

National Association of Realtors October 2022 Data

"More potential homebuyers were squeezed out from qualifying for a mortgage in October as mortgage rates climbed higher," said NAR Chief Economist Lawrence Yun. "The impact is greater in expensive areas of the country and in markets that witnessed significant home price gains in recent years."

Total housing inventory at the end of October was 1.22 million units, which was down 0.8% from both September and one year ago (1.23 million). Unsold inventory sits at a 3.3-month supply at the current sales pace, up from 3.1 months in September and 2.4 months in October 2021.

"Inventory levels are still tight, which is why some homes for sale are still receiving multiple offers," Yun added. "In October, 24% of homes received over the asking price. Conversely, homes sitting on the market for more than 120 days saw prices reduced by an average of 15.8%."
 
The median existing-home price for all housing types in October was $379,100, a gain of 6.6% from October 2021 ($355,700), as prices rose in all regions. This marks 128 consecutive months of year-over-year increases, the longest-running streak on record.
 
Properties typically remained on the market for 21 days in October, up from 19 days in September and 18 days in October 2021. Sixty-four percent of homes sold in October 2022 were on the market for less than a month.

First-time buyers were responsible for 28% of sales in October, down from 29% in both September 2022 and October 2021. NAR's 2022 Profile of Home Buyers and Sellers – released earlier this month – found that the annual share of first-time buyers was 26%, the lowest since NAR began tracking the data.

All-cash sales accounted for 26% of transactions in October, up from 22% in September and 24% in October 2021.

Individual investors or second-home buyers, who make up many cash sales, purchased 16% of homes in October, up from 15% in September, but down from 17% in October 2021.

 
According to Freddie Mac, the average commitment rate for a 30-year, conventional, fixed-rate mortgage was 6.90% in October, up from 6.11% in September. The average commitment rate across all of 2021 was 2.96%.
 
"Mortgage rates have come down since peaking in mid-November, so home sales may be close to reaching the bottom in the current housing cycle," Yun said.
 
Regional Breakdown
 
Existing-home sales in the Northeast trailed off 6.6% from September to an annual rate of 570,000 in October, a decline of 23.0% from October 2021. The median price in the Northeast was $408,700, an increase of 8.0% from the previous year.
 
Existing-home sales in the Midwest retracted 5.3% from the previous month to an annual rate of 1,080,000 in October, falling 25.5% from the prior year. The median price in the Midwest was $274,500, up 5.9% from October 2021.
 
In the South, existing-home sales declined 4.8% in October from September to an annual rate of 1,980,000, a 27.2% decrease from this time last year. The median price in the South was $346,300, an increase of 8.0% from one year ago.
 
Existing-home sales in the West waned 9.1% from September to an annual rate of 800,000 in October, down 37.5% from one year ago. The median price in the West was $588,400, a 5.3% increase from October 2021.


Mortgage Rates Are Dropping. What Does That Mean for You?

Mortgage rates have been a hot topic in the housing market over the past 12 months. Compared to the beginning of 2022, rates have risen dramatically. Now they’re dropping, and that has to do with everything happening in the economy.

Nadia Evangelou, Senior Economist and Director of Forecasting at the National Association of Realtors (NAR), explains it well by saying:

“Mortgage rates dropped even further this week as two main factors affecting today’s mortgage market became more favorable. Inflation continued to ease while the Federal Reserve switched to a smaller interest rate hike. As a result, according to Freddie Mac, the 30-year fixed mortgage rate fell to 6.31% from 6.33% the previous week.”

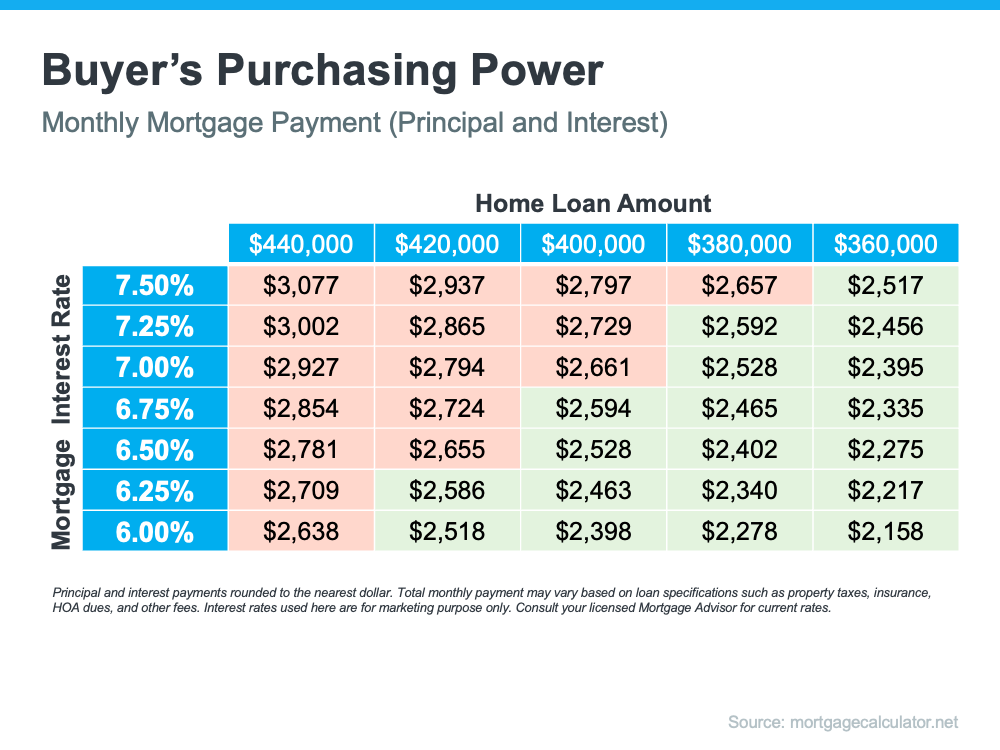
So, what does that mean for your homeownership plans? As mortgage rates fluctuate, they impact your purchasing power by influencing the cost of buying a home. Even a small dip can help boost your purchasing power. Here’s how it works.

The median-priced home according to the National Association of Realtors (NAR) is $379,100. So, let’s assume you want to buy a $400,000 home. If you’re trying to shop at that price point and keep your monthly payment about $2,500-2,600 or below, here’s how your purchasing power can change as mortgage rates move up or down (see chart below). The red shows payments above that threshold and the green indicates a payment within your target range.

Mortgage Rates Are Dropping. What Does That Mean for You? | MyKCM

This goes to show, even a small quarter-point change in mortgage rates can impact your monthly mortgage payment. That’s why it’s important to work with a trusted real estate professional who follows what the experts are projecting for mortgage rates for the days, months, and year ahead.

Bottom Line

Mortgage rates are likely to fluctuate depending on what happens with inflation moving forward, but they have dropped slightly in recent weeks. If a 7% rate was too high for you, it may be time to contact a lender to see if the current rate is more in line with your goal for a monthly housing expense.

Homeownership Is an Investment in Your Future

There are many people thinking about buying a home, but with everything affecting the economy, some are wondering if it’s a smart decision to buy now or if it makes more sense to wait it out. As Bob Broeksmit, President and CEO of the Mortgage Bankers Association (MBA), explains:

“The desire for homeownership is strong. Many prospective buyers are waiting for the volatility in mortgage rates to subside, as well as for a clearer picture of the economic outlook.”

If you’re in that position, remember that it’s important to consider not just what’s happening today but also what benefits you may gain in the long run.

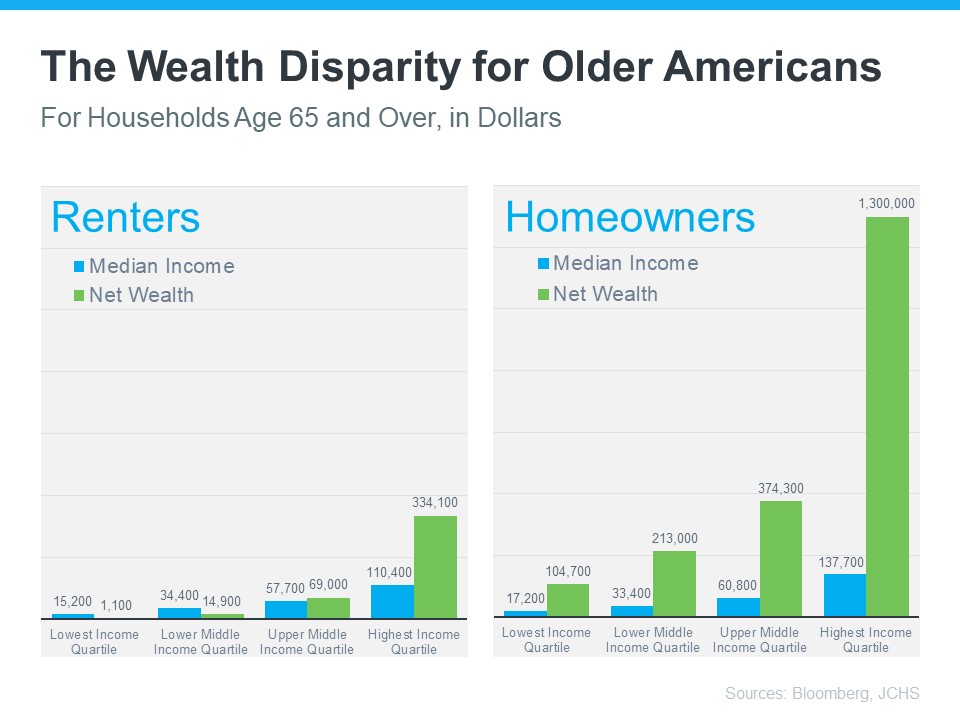
There’s a lot of information out there about how homeownership helps build a homeowner’s net worth over time. But even today, many people think first about things like 401(k)s before they think of owning a home as a wealth-building tool. It’s especially important if you’re a young prospective homebuyer to understand how homeownership is another key way to invest in your future. An article from Bloomberg notes:

“Millennials have higher average 401(k) balances than Generation X did when they were the same age, but they’re not any better off financially. . . . A lot of that has to do with being less likely to own a home.”

To help you understand just how much owning a home can have a positive impact on your life over the years, take a look at what the data shows. The same Bloomberg article helps show the gap in wealth between renters and homeowners who are 65 years and older (see graph below). The difference is substantial, even when incomes are similar.

Homeownership Is an Investment in Your Future | MyKCM

So, if you want to create wealth to help set you up for success later on, it may be time to prioritize homeownership. That’s because, whether you decide to rent or buy a home, you’ll have a monthly housing expense either way. The question is: are you going to invest in yourself and your future, or will you help someone else (your landlord) increase their wealth?

Bottom Line

Before putting your homeownership plans on hold, let’s connect to go over your options. That way, you’ll have expert advice on how to make the best decision right now and the best investment in your future.

What You Want To Know If You’re Pursuing Your Dream of Homeownership

If you’re a young adult, you may be thinking about your goals and priorities for the months and years ahead. And if homeownership ranks high on your goal sheet, you’re in good company. Many of your peers are also pursuing their dream of owning a home. The 2022 Millennial & Gen Z Borrower Sentiment Report from Maxwell says:

“Many young adults have demonstrated their resolve to embark on the journey toward homeownership soon. More than half of millennials and Gen Zs plan to apply for a mortgage sometime within the next year.”

Let’s take a look at why homeownership makes the top of so many young buyers’ to-do list and what you need to consider to achieve your goals if you’re one of them.

Top Motivators To Buy a Home

Before you start the homebuying process, it’s helpful to know why homeownership is so important to you. The survey mentioned above sheds light on some of the top reasons why younger generations are looking to buy a home. It finds:

No matter which of these resonates the most with you, know there are many financial and non-financial reasons why you may want to buy a home. While your top motivator may be different than that of your friends, they’re all equally valid and worthwhile.

Key Obstacles and How To Overcome Them

Whether your homeownership goals come from the heart or are driven by financial aspirations (or both), it can still be hard to know where to start when you’re looking to buy a home. From understanding the homebuying process, to getting pre-approved, and exploring down payment options, it’s a lot to wrap your head around.

The same Maxwell survey also reveals key challenges for potential buyers. Thankfully, the knowledge and guidance of a trusted real estate professional can help you overcome both. Here’s a look at two of the hurdles potential homebuyers say they face:

1. The Mortgage Process Can Be Intimidating

In the Maxwell study, 33.37% said one of their obstacles was that the mortgage process is confusing or difficult to understand.

An article by OwnUp helps explain why the mortgage process is so challenging for buyers:

“There is a general lack of knowledge about home financing. Mortgages are a complicated topic with no one-size-fits-all answer. It’s difficult to understand the space, let alone determine what the right course of action is based on your unique financial picture.”

While you may be tempted to do a quick search online to find instant answers to your questions, it may not get you the information you need to understand the full picture. Especially when it comes to financial advice, you want to lean on a true expert. Having trusted professionals on your side can help you to learn what it takes to achieve your dream of homeownership. Not to mention, an expert can give you advice specific to your situation, not generic advice like you’ll find online.

2. It’s Hard To Know How Much You Need To Save

In the Maxwell study, 45.75% believe they don’t have enough saved to cover their down payment or closing cost expenses.

What you may not realize is that, today, there’s a growing number of down payment assistance programs available nationwide to help relieve this pressure. A report from Down Payment Resource says:

“Our Q3 2022 HPI report revealed a 1.6% uptick in the number of homebuyer assistance programs available to help people finance homes, raising the number of programs to 2,309, a net increase of 36 over the previous quarter.”

Additionally, as the housing market cools, buyers are regaining some negotiation power and more sellers are willing to work with buyers to help with closing costs.  Understanding what’s out there and the options available may help you achieve your dream of homeownership faster than you thought possible.

Bottom Line

If you’re serious about becoming a homeowner, know it may be more in reach than you think. Lean on trusted professionals to help you overcome challenges and prioritize your next steps.

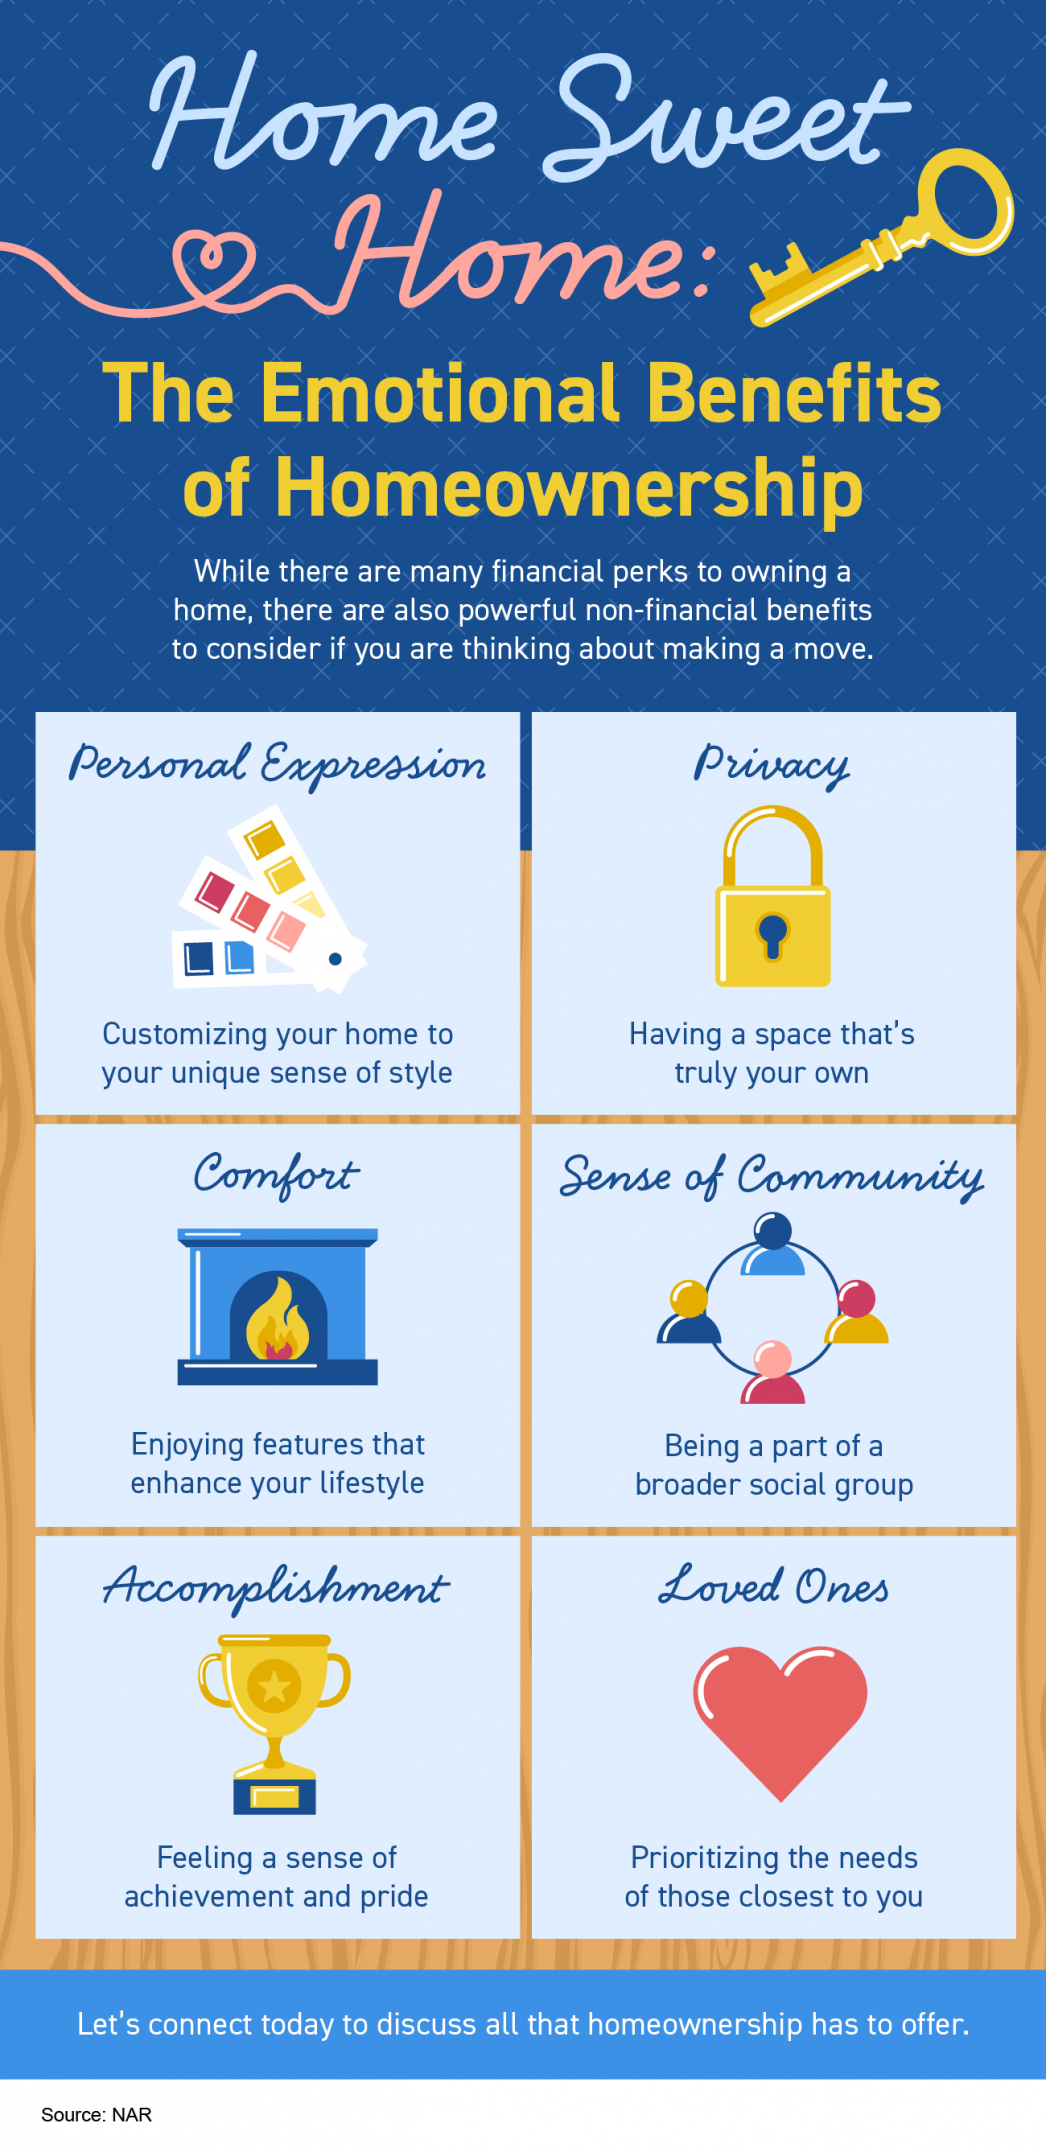
Home Sweet Home: The Emotional Benefits of Homeownership [INFOGRAPHIC]

Home Sweet Home: The Emotional Benefits of Homeownership [INFOGRAPHIC] | MyKCM

Some Highlights

  • While there are many financial perks to owning a home, there are also powerful non-financial benefits to consider if you’re thinking about making a move.
  • Homeownership allows you to express yourself, gives you greater privacy and comfort, enhances your connection to your community and loved ones, and is an achievement to feel proud of.
  • Let’s connect today to discuss all that homeownership has to offer.

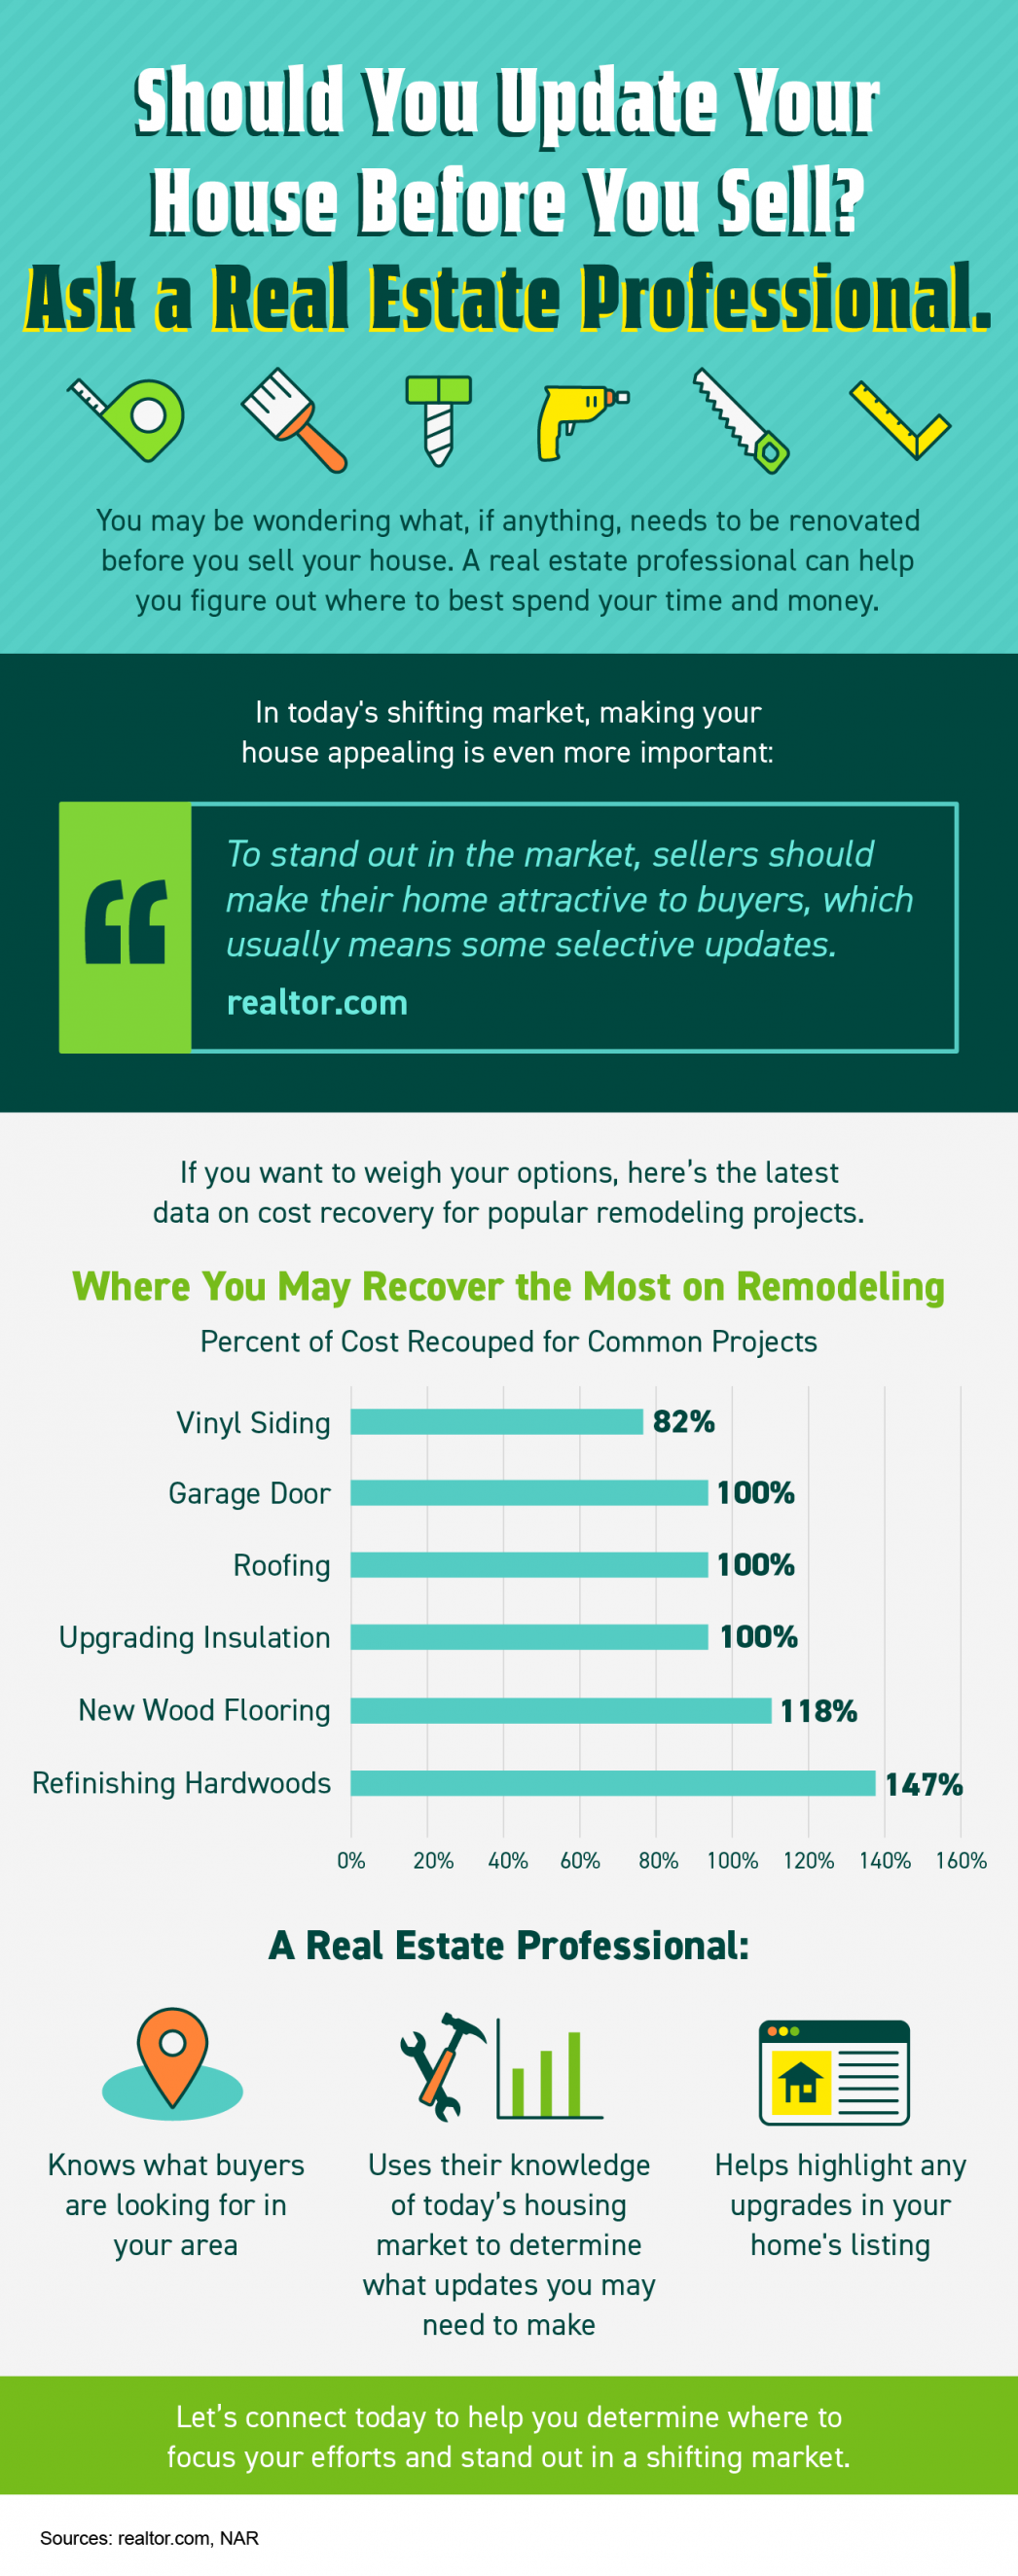
Should You Update Your House Before You Sell? Ask a Real Estate Professional. [INFOGRAPHIC]

Should You Update Your House Before You Sell? Ask a Real Estate Professional. [INFOGRAPHIC] | MyKCM

Some Highlights

  • You may be wondering what needs to be renovated before you sell your house. In today’s shifting market, making your house appealing is more important than ever.
  • That’s why it’s essential to lean on a real estate professional who has in-depth knowledge of today’s housing market. They know what buyers are looking for and how to highlight any upgrades you make.
  • Let’s connect so you know where to focus your efforts so your house will stand out in a today’s market.

VA Loans Can Help Veterans Achieve Their Dream of Homeownership

For over 78 years, Veterans Affairs (VA) home loans have provided millions of veterans with the opportunity to purchase homes of their own. If you or a loved one have served, it’s important to understand this program and its benefits.

Here are some things you should know about VA loans before you start the homebuying process.

What Are VA Loans?

VA home loans provide a pathway to homeownership for those who have served our nation. The U.S. Department of Veterans Affairs describes the program like this:

“VA helps Servicemembers, Veterans, and eligible surviving spouses become homeowners. As part of our mission to serve you, we provide a home loan guaranty benefit and other housing-related programs to help you buy, build, repair, retain, or adapt a home for your own personal occupancy.”

Top Benefits of the VA Home Loan Program

In addition to helping eligible buyers achieve their homeownership dreams, VA loans have several other great benefits for buyers who qualify. According to the Department of Veteran Affairs:

  • Qualified borrowers can often purchase a home with no down payment.
  • Many other loans with down payments under 20% require Private Mortgage Insurance (PMI). VA Loans do not require PMI, which means veterans can save on their monthly housing costs.
  • VA-Backed Loans often offer competitive terms and mortgage interest rates.

A recent article from Veterans United sums up just how impactful this loan option can be:

“For the vast majority of military borrowers, VA loans represent the most powerful lending program on the market. These flexible, $0-down payment mortgages have helped more than 24 million service members become homeowners since 1944.”

John Bell, Acting Executive Director of the Department of Veterans Affairs Loan Guaranty Service, also explains why this program is so powerful:

“It provides early ownership for many people that would not have that opportunity to begin with. Since there’s no down payment, it allows people to hold their wealth and it gives them the ability to have long term financial security by being able to own a house and let that equity grow.”

Bottom Line

Homeownership is the American Dream. Our veterans sacrifice so much in service of our nation, and one way we can honor and thank them is to ensure they have the best information about the benefits of VA home loans. Thank you for your service.

Do You Believe Homeownership Is Out of Reach? Maybe It Doesn’t Have To Be.

It turns out, millennials aren’t the renter generation after all. The 2022 Consumer Insights Report from Mynd says there’s a portion of millennial and Gen Z buyers who are pursuing homeownership as a way to build their wealth, but it may not be exactly the way previous generations have done it. The study explains how they’re breaking into the market:

“. . . younger generations of Americans are not buying into that dream in the same way that older generations have. A growing number of Americans are choosing to make their first real estate purchase as an investment property.”

Instead of buying a home and moving into it themselves, some young buyers are purchasing a home so they can use it as a rental. This tactic may be gaining popularity, at least in part, because of the affordability challenges brought about by today’s higher mortgage rates. The report above mentions how many people in this group are considering this approach. It says:

“Almost half of Millennials and Gen Z (43%) are considering buying an investment property compared to only 9% of Baby Boomers and 27% of Gen X.”

Why Younger Buyers Are Buying a Home To Use as a Rental

This strategy allows buyers to continue living in their current location, like the bustle of a city apartment or a neighborhood that they know and love, where they couldn’t afford to buy. But instead of giving up on the idea of owning a home, they buy a home in a more affordable area with the intention of renting it out.

In a way, they’re getting the best of both worlds. They live where they want, and they still own a home where they can afford it.

Their goal is to generate passive income and diversify their assets. It works like this: in addition to having a rental stream of income, the equity they build in their house will also help grow their net worth over time.

Bottom Line

If you’re thinking about buying a home as an investment strategy to build your wealth, let’s connect to explore your options and nearby areas that may have homes that fit what you’re looking for.

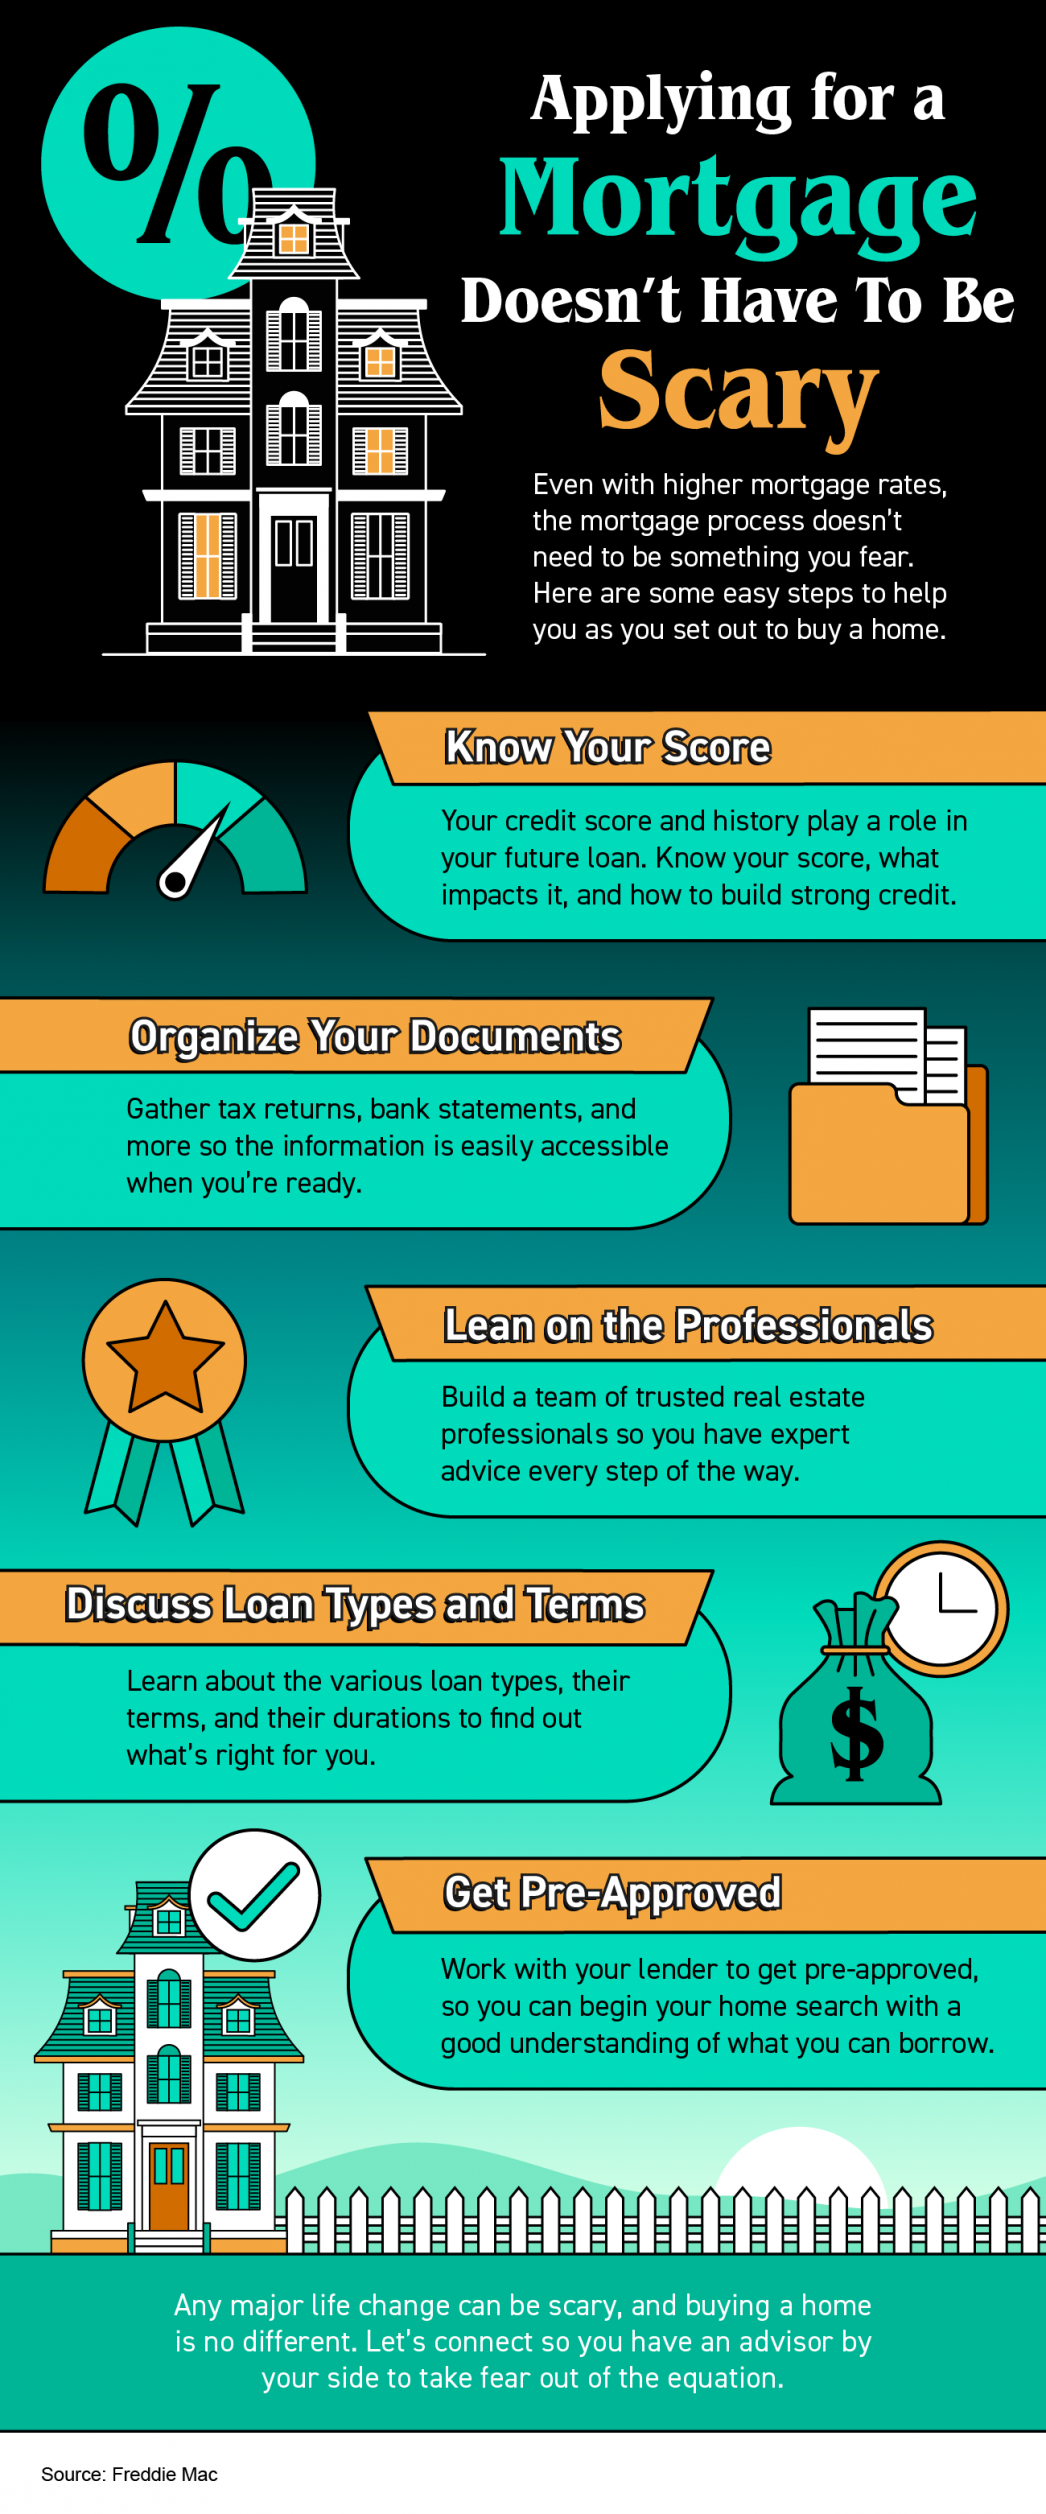
Applying for a Mortgage Doesn’t Have To Be Scary [INFOGRAPHIC]

Applying for a Mortgage Doesn’t Have To Be Scary [INFOGRAPHIC] | MyKCM

Some Highlights

  • Even with higher mortgage rates, the mortgage process doesn’t need to be something you fear. Here are some steps to help as you set out to buy a home.
  • Know your credit score and work to build strong credit. When you’re ready, lean on the pros and connect with a lender so you can get pre-approved and begin your home search.
  • Any major life change can be scary, and buying a home is no different. Let’s connect so you have an advisor by your side to take fear out of the equation.

August 2022 Market Update

Note: August 2022 data below are the most recent released by the National Association of Realtors.

Total existing-home sales) completed transactions that include single-family homes, townhomes, condominiums and co-ops) notched a minor contraction of 0.4% from July to a seasonally adjusted annual rate of 4.80 million in August. Year-over-year, sales faded by 19.9% (5.99 million in August 2021).

National Association of Realtors August 2022 Data

"The housing sector is the most sensitive to and experiences the most immediate impacts from the Federal Reserve's interest rate policy changes," said NAR Chief Economist Lawrence Yun. "The softness in home sales reflects this year's escalating mortgage rates. Nonetheless, homeowners are doing well with near nonexistent distressed property sales and home prices still higher than a year ago."

Total housing inventory at the end of August was 1,280,000 units, a decrease of 1.5% from July and unchanged from the previous year. Unsold inventory sits at a 3.2-month supply at the current sales pace – identical to July and up from 2.6 months in August 2021.

"Inventory will remain tight in the coming months and even for the next couple of years," Yun added. "Some homeowners are unwilling to trade up or trade down after locking in historically-low mortgage rates in recent years, increasing the need for more new-home construction to boost supply."
 
The median existing-home price for all housing types in August was $389,500, a 7.7% jump from August 2021 ($361,500), as prices ascended in all regions. This marks 126 consecutive months of year-over-year increases, the longest-running streak on record. However, it was the second month in a row that the median sales price retracted after reaching a record high of $413,800 in June, the usual seasonal trend of prices declining after peaking in the early summer.
 
Properties typically remained on the market for 16 days in August, up from 14 days in July and down from 17 days in August 2021. Eighty-one percent of homes sold in August 2022 were on the market for less than a month.

First-time buyers were responsible for 29% of sales in August, consistent with July 2022 and August 2021. NAR's 2021 Profile of Home Buyers and Sellers  – released in late 2021 – reported that the annual share of first-time buyers was 34%.

All-cash sales accounted for 24% of transactions in August, the same share as in July, but up from 22% in August 2021.

Individual investors or second-home buyers, who make up many cash sales, purchased 16% of homes in August, up from 14% in July and 15% in August 2021.

 
According to Freddie Mac, the average commitment rate for a 30-year, conventional, fixed-rate mortgage was 5.22% in August, down from 5.41% in July. The average commitment rate across all of 2021 was 2.96%.
 
"In a sense, we're seeing a return to normalcy with the homebuying process as it relates to home inspections and appraisal contingencies, as those crazy bidding wars have essentially stopped," said NAR President Leslie Rouda Smith, a REALTOR® from Plano, Texas, and a broker associate at Dave Perry-Miller Real Estate in Dallas. "In an ever-changing market, REALTORS® help consumers successfully manage the complexities of buying or selling homes."
 
Regional Breakdown
 
Existing-home sales in the Northeast grew 1.6% from July to an annual rate of 630,000 in August, down 13.7% from August 2021. The median price in the Northeast was $413,200, an increase of 1.5% from the previous year.
 
Existing-home sales in the Midwest fell 3.3% from the prior month to an annual rate of 1,160,000 in August, retreating 15.9% from August 2021. The median price in the Midwest was $287,900, up 6.6% from the previous year.
 
At an annual rate of 2,130,000 in August, existing-home sales in the South were identical to July but down 19.3% from one year ago. The median price in the South was $356,000, an increase of 12.4% from August 2021.
 
Existing-home sales in the West expanded 1.1% compared to last month to an annual rate of 880,000 in August, down 29.0% from this time last year. The median price in the West was $602,900, a 7.1% increase from August 2021.