
Real Estate: It’s Still a Lack of Supply, Not a Lack of Demand

One of the major questions real estate experts are asking today is whether prospective homebuyers still believe purchasing a home makes sense. Some claim rapidly rising home prices are impacting demand and, by extension, leading to the recent slowdown in sales activity.

However, demand isn’t the real issue. Instead, it’s the lack of supply (homes available for sale). An article from the Wall Street Journal shows this is true for new home construction:

“Home builders have sold more homes than they can build. Now they are limiting their sales in an effort to catch up.”

The article quotes David Auld, CEO of D.R. Horton Inc. (the largest homebuilder by volume in the United States since 2002), explaining how they don’t have enough homes for the number of buyers coming into their models:

“Through our history, to have somebody walk into our models and to tell them, ‘We don’t have a house for you to buy today’, is something that is foreign to us.”

Danielle Hale, Chief Economist for realtor.com, also explains that, in the existing home sale market, the slowdown in sales was a supply challenge, not a lack of demand. Responding to a recent uptick in listings coming to market, she notes:

“. . . if these changing inventory dynamics continue, we could see a wave of real estate activity heading into the latter part of the year.”

Again, the buyers are there. We just need houses to sell to them.

If the slowdown in sales was the result of demand waning, we would start to see home prices beginning to moderate – but this isn’t the case. As Mark Fleming, Chief Economist for First American, explains:

“There’s a lot of conversation around rising prices and falling quantity in the housing market, and there’s this concept, or this idea, that it’s a demand-side problem . . . . But, if demand were falling dramatically, we would actually see less price pressure, less home price growth.”

Instead, we’re seeing price appreciation accelerate throughout this year, as evidenced by the year-over-year percentage increases reported by CoreLogic:

  • January: 10%
  • February: 10.4%
  • March: 11.3%
  • April: 13%
  • May: 15.4%
  • June: 17.2%

(July numbers are not yet available)

There’s a shortage of listings, not buyers, and there are three very good reasons for purchasers to still be interested in buying a home this year.

  1. Affordability isn’t the challenge some are claiming it to be.

Though home prices have risen dramatically over the last 18 months, mortgage rates remain near historic lows. Because of these near-record rates, monthly mortgage payments are affordable for most buyers.

While homes are less affordable than they were last year, when we adjust for inflation, we can see they’re also more affordable than they were in the 1970s, 1980s, 1990s, and much of the 2000s.

  1. Owning is a better long-term decision than renting.

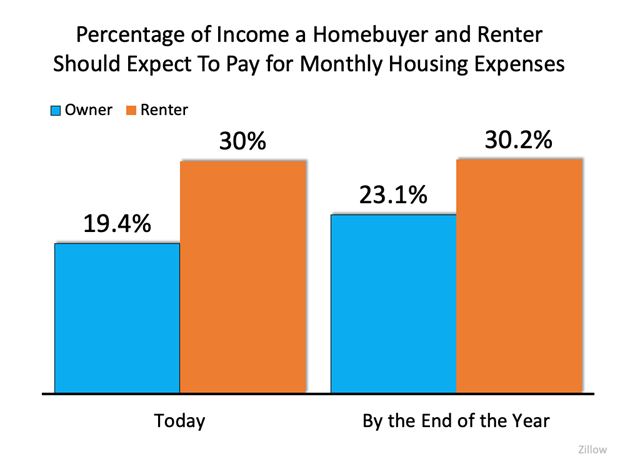
A recent study shows renting a home takes up a higher percentage of a household’s income than owning one. According to the analysis, here’s the percentage of income homebuyers and renters should expect to pay now versus at the end of the year.While the principal and interest of a monthly mortgage payment remain the same over the lifetime of the loan, rents increase almost every year.
Real Estate: It’s Still a Lack of Supply, Not a Lack of Demand | North Scottsdale Real Estate & Luxury Homes | Team Picarello


  1. Owners build their wealth. Renters build their landlord’s wealth.

Whether you’re a homeowner or an investor, real estate builds wealth through growing equity year-over-year. If you own, your household is gaining the benefit of that wealth accumulation. Fleming says:

“The major financial advantage of homeownership is the accumulation of equity in the form of house price appreciation . . . . We have to take into account the fact that the shelter that you’re owning is an equity-generating or wealth-generating asset.”

Odeta Kushi, Deputy Chief Economist at First American, elaborates in a recent article:

“. . . once the home is purchased, appreciation helps build equity in the home, and becomes a benefit rather than a cost. When accounting for the appreciation benefit in our rent versus own analysis, it was cheaper to own in every one of the top 50 markets, including the two most expensive rental markets, San Francisco and San Jose, Calif.”

Today, that equity buildup is substantial. The National Association of Realtors (NAR) reports:

“The median sales price of single-family existing homes rose in 99% of measured metro areas in the second quarter of 2021 compared to one year ago, with double-digit price gains in 94% of markets.”

In 94% of markets, there was a greater than 10% increase in median price. That means if you bought a $400,000 home in one of those markets, your net worth increased by at least $40,000. If you rented, the landlord was the recipient of the wealth increase.

Bottom Line

For many reasons, housing demand is still extremely strong. What we need is more supply (house listings) to meet that demand.
Are Houses Less Affordable Than They Were in Past Decades?

There are many headlines about how housing affordability is declining. The headlines are correct: it’s less affordable to purchase a home today than it was a year ago. However, it’s important to give this trend context. Is it less expensive to buy a house today than it was in 2005? What about 1995? What happens if we go all the way back to 1985? Or even 1975?

Obviously, the price of a home has appreciated dramatically over the last 45 years. So have the prices of milk, bread, and just about every other consumable. Prices rise over time – we know it as inflation.

However, when we look at housing, price is just one component that makes up the monthly cost of the home. Another key factor is the mortgage rate at the time of purchase.

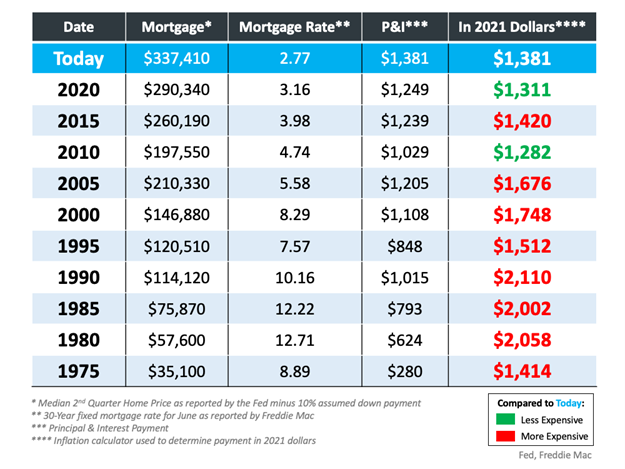
Let’s look back at the cost of a home over the last five decades and adjust it for inflation by converting that cost to 2021 dollars. Here’s the methodology for each data point of the table below:
• Mortgage Amount: Take the median sales price at the end of the second quarter of each year as reported by the Fed and assume that the buyer made a 10% down payment.
• Mortgage Rate: Look at the monthly 30-year fixed rate for June of that year as reported by Freddie Mac.
• P&I: Use a mortgage calculator to determine the monthly principal and interest on the loan.
• In 2021 Dollars: Use an inflation calculator to determine what each payment would be when adjusted for inflation. Green means the homes were less expensive than today. Red means they were more expensive.

Are Houses Less Affordable Than They Were in Past Decades? | North Scottsdale Real Estate & Luxury Homes | Team Picarello
As the chart shows, when adjusted for inflation, there were only two times in the last 45 years that it was less expensive to own a home than it is today.
1. Last year: Prices saw strong appreciation over the last year and mortgage rates have remained relatively flat. Therefore, affordability weakened.
2. 2010: Home values plummeted after the housing crash 15 years ago. One-third of all sales were distressed properties (foreclosures or short sales). They sold at major discounts and negatively                impacted the value of surrounding homes – of course homes were more affordable then.

At every other point, even in 1975, it was more expensive to buy a home than it is today.

Bottom Line
If you want to buy a home, don’t let the headlines about affordability discourage you. You can’t get the deal your friend got last year, but you will get a better deal than your parents did 20 years ago and your grandparents did 40 years ago.

June 2021 Market Update

Note: June 2021 data below are the most recent released by the National Association of Realtors.

Existing-home sales increased in June, snapping four consecutive months of declines, according to the National Association of Realtors®. Three of the four major U.S. regions registered small month-over-month gains, while the fourth remained flat. However, all four areas notched double-digit year-over-year gains.

Total existing-home sales (transactions that include single-family homes, townhomes, condominiums and co-ops) grew 1.4% from May to a seasonally adjusted annual rate of 5.86 million in June. Sales climbed year-over-year, up 22.9% from a year ago (4.77 million in June 2020).

National Association of Realtors June 2021 Data

"Supply has modestly improved in recent months due to more housing starts and existing homeowners listing their homes, all of which has resulted in an uptick in sales," said Lawrence Yun, NAR's chief economist. "Home sales continue to run at a pace above the rate seen before the pandemic."

Total housing inventory at the end of June amounted to 1.25 million units, up 3.3% from May's inventory and down 18.8% from one year ago (1.54 million). Unsold inventory sits at a 2.6-month supply at the current sales pace, modestly up from May's 2.5-month supply but down from 3.9 months in June 2020.

The median existing-home price for all housing types in in June was $363,300, up 23.4% from June 2020 ($294,400), as every region recorded price jumps. This marks 112 straight months of year-over-year gains.

"At a broad level, home prices are in no danger of a decline due to tight inventory conditions, but I do expect prices to appreciate at a slower pace by the end of the year," Yun said. "Ideally, the costs for a home would rise roughly in line with income growth, which is likely to happen in 2022 as more listings and new construction become available."

Properties typically remained on the market for 17 days in June, unchanged from May and down from 24 days in June 2020. Eighty-nine percent of homes sold in June 2021 were on the market for less than a month.

First-time buyers were responsible for 31% of sales in June, also even with May but down from 35% in June 2020. NAR's 2020 Profile of Home Buyers and Sellers revealed that the annual share of first-time buyers was 31%.

Individual investors or second-home buyers, who account for many cash sales, purchased 14% of homes in June, down from 17% in May and up from 9% in June 2020. All-cash sales accounted for 23% of transactions in June, even with May and up from 16% in June 2020.

"Huge wealth gains from both housing equity and the stock market have nudged up all-cash transactions, but first-time buyers who need mortgage financing are being uniquely challenged with record-high home prices and low inventory," Yun explained. "Although rates are favorably low, these hurdles have been overwhelming to some potential buyers."
 
According to Freddie Mac, the average commitment rate for a 30-year, conventional, fixed-rate mortgage was 2.98% in June, slightly up from 2.96% in May. The average commitment rate across all of 2020 was 3.11%.

"NAR continues our conversations with policymakers and leaders from across the industry in an effort to boost housing inventory and increase access to safe, affordable housing for all Americans," said NAR President Charlie Oppler, a Realtor® from Franklin Lakes, N.J., and the CEO of Prominent Properties Sotheby's International Realty. "As the nation's economy continues to recover from COVID-19, securing policies that are in the best interest of U.S. consumers and homeowners remains NAR's priority."